
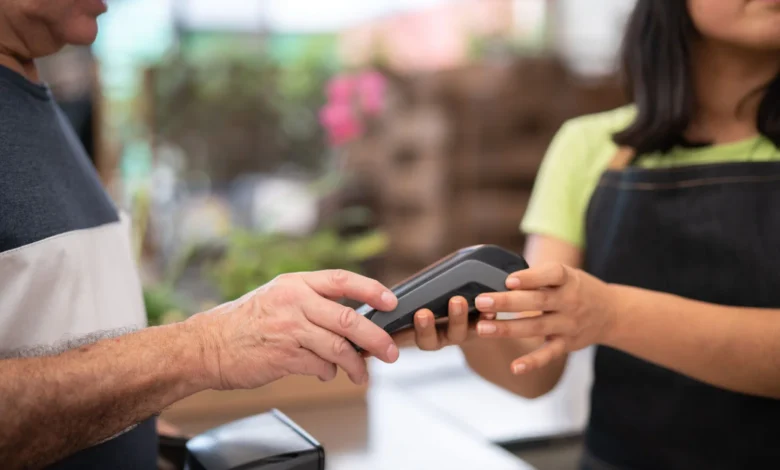
If you have paid by card at a shop or online lately, you may have noticed something missing: the extra fee at the end. Since 1 October 2026, businesses can no longer add a surcharge just because you pay with Visa, Mastercard, eftpos or American Express. The price you see is now the price you pay by card.
This change came from the Reserve Bank of Australia, which announced the reforms back on 31 March 2026. Here is what actually changed, what has not, and what it means for you. (The full official guidance is on the ACCC’s page on card surcharges.)
What changed on 1 October 2026
From that date, a business cannot charge you extra simply for paying by card on the main networks: eftpos, Mastercard, Visa and American Express. That covers credit, debit and prepaid cards — and it includes cards stored in mobile wallets, not just the plastic ones in your pocket.
A few other providers, including UnionPay, PayPal and JCB, have removed surcharging from the same date as well.
It was not always like this. Until the end of September, businesses were allowed to add a card surcharge as long as it did not go above what it actually cost them to accept the card. Those old “excessive surcharge” rules ended on 1 October 2026, and the surcharge itself went with them.
The Reserve Bank made other changes at the same time: the cap on interchange fees for consumer credit cards dropped from 0.8% to 0.3%, and the RBA estimates the changes will save consumers around $1.6 billion a year.
What has not changed
The ban covers card payment fees only. These charges are still allowed:
- Weekend and public holiday surcharges — cafés and restaurants can still add their usual 10–15% on Sundays and public holidays, because that surcharge has nothing to do with how you pay.
- Booking fees and service fees — as long as they apply no matter which payment method you choose.
One thing to watch: a business cannot just rename the old card fee and keep charging it. Calling it a “processing fee” or a “service charge” when it is really a card surcharge is misleading conduct under Australian Consumer Law.
What it means for shoppers
The simple version: the displayed price is now your card price. No more surprises at the checkout.
But the cost of taking cards has not disappeared — it has just moved. Many businesses will fold their card fees into their prices, so some things may get slightly more expensive. And banks are already making rewards cards less generous to make up for the lower fees they earn: fewer points, higher annual fees, or fewer perks.
If you still see a card surcharge: it should not be there. Start by asking the business — it may be an old setting on their card machine that was never switched off. If they will not fix it, you can report misleading pricing to the ACCC or your state consumer protection agency.
What it means for business owners
If you run a business that takes cards, here is your checklist:
- Switch surcharging off everywhere — your card terminal, point-of-sale system, online checkout, payment links and invoicing. Changing the terminal alone does not always update the online checkout, so check every channel and run a test transaction.
- Decide how to cover the cost. You can absorb the card fees, or build them into your prices. The ACCC’s own example: a hair salon charging $60 with a 1.0% card surcharge would move to $60.60 after folding the fee into the price. And do not blame the surcharge ban if your prices rise for other reasons too — saying the increase is “because of the surcharge ban” when it also reflects rent, wages or energy costs is misleading.
- Update everything customers see — signage, websites, invoices, quote templates and receipts that mention card surcharges.
- Brief your staff so they can answer customer questions.
- Consider cash or PayID discounts — these are still allowed, but the full price must be clearly displayed, and the discounted price cannot be shown as more prominent than the real price.
One last detail: the “no surcharge” rules are enforced by the card networks and your payment provider through your merchant agreement — the ACCC enforces the misleading-pricing rules, not the surcharge ban itself.
The bottom line
The card surcharge ban is a genuine win at the checkout: the price on the tag is the price you pay. The trade-off is that the cost of card payments has not vanished — it will show up in slightly higher prices and leaner rewards cards over time. For shoppers, it means simpler, more honest pricing. For businesses, it means one less line item — and one more thing to get right on the price tag.