Most of us have had that moment: payday arrives, the money feels like plenty, and then somehow, a week before the next payday, the account is nearly empty. Nothing big was bought. Nothing went wrong. The money just… went.
That is exactly why budgeting is important. A budget is simply a plan for your money. It shows you what comes in, what goes out, and what is left for the things that matter. Without one, you are guessing. With one, you are in charge. If you want a free tool to get started, ASIC’s Moneysmart budget planner walks you through the whole thing in under ten minutes.
Quick answer: Budgeting is important because it stops you spending more than you earn, makes sure your bills are covered, helps you save for real goals, and takes a huge amount of stress out of money. It is not about cutting out everything fun. It is about giving every dollar a job.
What Is Budgeting, in Simple Terms?
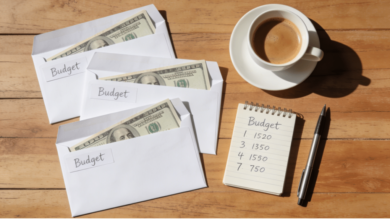
A budget is a written plan for your money over a set period — usually a week, a fortnight, or a month. You list your income, list your spending, and compare the two. That is it. There is no magic to it, and it does not need a spreadsheet full of formulas. A notebook works just as well as an app.
The point is not to track every cent forever. The point is to know, before the month starts, where your money will go — instead of wondering where it went at the end of it. Our guide on how budgeting works explains the basics step by step if you are starting from zero.
10 Reasons Why Budgeting Is Important
1. You finally see where your money goes
This is the first thing a budget does, and it surprises almost everyone. Small spending adds up fast: a coffee here, a food delivery there, a subscription you forgot about. When you write it all down, the leaks become obvious. You cannot fix a problem you cannot see, and a budget makes your spending visible.
2. You stop spending more than you earn
Overspending rarely happens in one big purchase. It happens in dozens of small ones. A budget sets a clear limit for each part of your life — groceries, transport, fun — so you know when to stop. Spending less than you earn is the foundation of everything else on this list.
3. Your bills get paid on time
Rent, power, phone, insurance, loan repayments: the regular bills do not wait. A budget puts them first, before the optional spending. That means fewer late fees, fewer reminder notices, and no nasty surprise when a quarterly bill lands. Moneysmart puts it simply: a budget helps you avoid running out of money before payday.
4. You build an emergency fund before you need one
The car breaks down. A tooth cracks. The washing machine dies. Life throws these at everyone, and they always seem to arrive at the worst time. A budget lets you put a small amount aside every payday, so an unexpected cost is an annoyance instead of a crisis. Even $20 or $50 a week adds up over a year.
5. You pay off debt faster
Credit card interest and personal loan interest are expensive, and minimum repayments keep you in debt for years. When you budget, you can see exactly how much extra you can put toward a debt each month — and watch the balance fall. Paying off high-interest debt first saves real money in interest.
6. You save for the things that actually matter
A holiday, a home deposit, a new car, your kids’ education, retirement: none of these happen by accident. They happen because money was set aside for them on purpose, month after month. A budget turns a vague wish (“one day I’d like to…”) into a plan with a date on it.
7. You feel less stressed about money
Money worries are one of the biggest sources of stress, and most of that stress comes from not knowing. Not knowing if the bills are covered. Not knowing if you can afford something. A budget replaces that uncertainty with a clear picture. Even a tight budget feels better than no plan at all, because you know exactly where you stand.
8. You spot waste and cut it without feeling deprived
Budgeting is not about giving up everything you enjoy. It is about finding the spending that adds nothing to your life — the second streaming service nobody watches, the gym membership nobody uses, the takeaway habit that started as a treat and became a routine. Cutting those frees up money for the things you actually enjoy.
9. You reach big goals sooner
Goals without a plan stay dreams. A budget gives each goal a monthly amount and a finish line. Want a home deposit? The budget shows how much you can save each month and how long it will take. Want to retire comfortably? Regular contributions to your super, planned in your budget, grow over decades. Small, steady amounts beat big, irregular ones.
10. You stay in control when life changes
Jobs change. Hours get cut. Prices go up. Kids arrive. When your situation changes, a budget is the tool that lets you adjust quickly — you can see exactly what needs to change, instead of panicking. People with a budget adapt. People without one often only notice the problem when the account is already empty.
What Happens If You Don’t Budget?
Nothing dramatic — at first. That is the problem. Without a budget, the damage is slow and quiet: a little overspending here, a missed savings month there, a credit card balance that creeps up. Then one unexpected bill arrives and there is nothing to cover it, so it goes on the card, and the interest starts compounding.
Over time, that pattern leads to real trouble: growing debt, late fees, a damaged credit score, and constant low-level worry about money. A budget is the simplest way to stop that slide before it starts.
How to Start Budgeting in 10 Minutes
You do not need a perfect system. You need a start. Here is a simple way to do it today:
Step 1: Write down your income. Your take-home pay, plus any other regular money coming in.
Step 2: List your regular expenses. Rent or mortgage, bills, groceries, transport, insurance, loan repayments.
Step 3: See what is left. Income minus expenses is the money you can save, spend on fun, or put toward debt.
Step 4: Give it a simple split. A popular starting point is the 50/30/20 rule — about 50% of your pay on needs (rent, bills, groceries), 30% on wants (eating out, streaming, hobbies), and 20% on savings and paying down debt. The rule was popularised by Elizabeth Warren’s 2005 book All Your Worth, and it works well as a rough guide. Adjust the percentages to fit your life.
Step 5: Check in once a week. Five minutes is enough. Are you on track? Did anything change? Adjust as you go. A budget is a living plan, not a set of rules carved in stone.
If you want a guided version, our step-by-step guide on how to create a budget walks through the whole process, and our roundup of the best free budgeting apps can do the adding up for you.
Common Budgeting Mistakes to Avoid
Making it too strict. A budget with zero fun money fails within weeks. Leave room for the things you enjoy, or you will abandon the whole plan.
Forgetting irregular costs. Car rego, insurance renewals, Christmas, school fees — these are not surprises if you plan for them. Set aside a little each month for the costs that only come once or twice a year.
Never checking it. A budget you write once and never look at is just a piece of paper. A quick weekly check is what makes it work.
Quitting after one bad month. Everyone blows the budget sometimes. One bad month is not failure — it is information. Look at what happened, adjust, and keep going.
FAQs About Budgeting
Is budgeting only for people who are struggling with money?
No. Budgeting helps at every income level. People on good incomes overspend too — often more, because the money feels endless until it is not. A budget is for anyone who wants their money to go where they choose, not where it drifts.
How much should I save each month?
There is no single right number. A common target is around 20% of your take-home pay for savings and extra debt payments, but any regular amount is a good start. Even a small amount saved consistently beats a big amount saved once and never again.
Do I need a budgeting app?
No. A notebook, a simple spreadsheet, or your bank’s own app can all work. Apps help because they do the maths and show your spending automatically, but the tool matters far less than the habit. Pick whatever you will actually use.
How often should I check my budget?
Once a week is plenty for most people, plus a proper review once a month. The weekly check catches problems early, and the monthly review lets you adjust for the month ahead.
Budgeting is important because it turns money from a source of stress into a tool you control. It shows you where your money goes, keeps your bills covered, builds a safety net for the unexpected, and moves you steadily toward the goals that matter to you. Start small, keep it simple, and check in weekly — that is all it takes.
This article is general information only and is not personal financial advice. If you need help with debt or a difficult financial situation, a free financial counsellor can help — call the National Debt Helpline on 1800 007 007.