
A novated lease can be one of the cheapest ways for an employee to get a new car — or an expensive lesson in reading the fine print. The honest answer to “is a novated lease worth it?” is: yes, for many people, but not for everyone. It comes down to three things: how much you earn, which car you choose, and how stable your job is. New to the concept? Read our plain-English guide on what a novated lease is first.
The Short Answer
A novated lease is usually worth it if you earn a moderate to high salary, your employer offers salary packaging, and you were going to buy a new or near-new car anyway. The tax saving comes from paying the lease and running costs from your pre-tax salary, which lowers your taxable income. For eligible electric vehicles, the deal is even sweeter because they are exempt from fringe benefits tax (FBT) entirely. It is usually NOT worth it if you are on a low income, you change jobs often, you drive an old banger you plan to keep, or the finance rate in the lease quote is much higher than a regular car loan.
When a Novated Lease Is Worth It
You earn enough for the tax saving to matter. The whole point of a novated lease is the income tax saving. If you are in a higher marginal tax bracket, every dollar paid pre-tax saves you more. As a rough rule, it becomes attractive once you earn above about $45,000 a year. On lower incomes the saving can be too small to justify the lease fees and the loss of flexibility.
You were going to buy a car anyway. A novated lease is a financing method, not a reason to buy a more expensive car. If you already planned to buy a new car with a loan, the novated route usually wins on total cost because of the tax and GST savings.
You like predictable costs. Fuel, servicing, tyres, insurance and registration get bundled into one regular payment taken from your salary. No surprise $1,200 tyre bills. For people who budget carefully, this alone is worth a lot.
You upgrade cars every few years. Novated leases typically run 1 to 5 years, which suits drivers who like a new car every few years. At the end you can pay the residual and keep the car, refinance the residual, or roll into a new lease.
When It Is NOT Worth It
Your job situation is shaky. A novated lease is a three-way agreement between you, your employer and the finance company. If you leave your job, the lease does not just disappear — you keep paying it from your own pocket, or you renegotiate it with a new employer. People who change jobs often or work casually should think twice.
The finance rate is high. This is the catch most people miss. Novated lease providers charge their own interest rates and fees, and these can be higher than a standard car loan. A cheap-looking tax saving can be wiped out by an expensive interest rate. Always compare the lease’s effective rate against the best car loan you could get yourself.
You drive very little. Part of the saving comes from paying running costs pre-tax. If you barely drive, those running costs are small, and so is the saving — while the lease fees stay the same.
You want to own the car outright from day one. With a lease there is always a balloon (residual) payment hanging over the end of the term. If you hate owing money and just want to pay cash and be done, do that.
The Two Catches Nobody Explains Clearly
1. Fringe benefits tax (FBT)
Because your employer is technically providing you a car as a benefit, FBT can apply — currently charged at 47% of the taxable value of the benefit. Most non-EV novated leases deal with this using the “employee contribution method”: you pay a portion of the costs from your post-tax salary to cancel out the FBT liability. It works, but it eats into your saving, especially on petrol and diesel cars. (Eligible electric vehicles skip this entirely — more on that below.)
2. The residual (balloon) payment
At the end of the lease you owe a lump sum — the residual — set by ATO minimum guidelines. For a 5-year lease it is 28.13% of the car’s original price; 37.50% for 4 years; 46.88% for 3 years; 56.25% for 2 years; and 65.63% for 1 year. On a $40,000 car over 5 years, that is about $11,250 still owing at the end. This is not extra profit for the lender — it is part of the car’s price you have not paid yet. But you need a plan for it: pay it and keep the car, refinance it, or trade the car in. If the car’s market value has dropped below the residual, that is your problem, not the lender’s.
Electric Cars Change the Maths
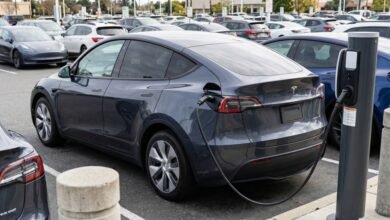
This is the biggest reason novated leases have become so popular. Eligible electric vehicles are exempt from FBT under the government’s electric car discount. That removes the biggest catch above: the entire lease — including electricity, registration, insurance and servicing — can come from pre-tax salary with no FBT to offset. On a mid-priced EV this can save thousands of dollars a year compared with buying the same car with a loan. The EV must be under the luxury car tax threshold for fuel-efficient vehicles (which the ATO updates each year), so check the current figure before you commit. For petrol and diesel cars, the savings are real but more modest — and the finance rate matters more.
Novated Lease vs Car Loan: Quick Comparison
| Novated Lease | Car Loan | |
|---|---|---|
| Tax saving | Yes, via pre-tax salary | No |
| GST saving on car price | Yes, up to thousands | No |
| Running costs | Bundled, paid pre-tax | Paid separately, after tax |
| Upfront cost | Usually $0 deposit | Deposit often needed |
| Employer needed | Yes | No |
| End of term | Residual payment due | You own the car |
| If you change jobs | Lease may need renegotiating | No impact |
| Interest rates | Set by provider, compare carefully | Shop around yourself |
What to Check Before You Sign
Get the lease provider’s quote in writing and check these five things: the effective interest rate (not just the monthly payment); all fees — establishment, monthly admin and early payout fees; the residual amount in dollars, not just a percentage; what happens to the lease if you leave your job; and whether the car you want is FBT-exempt (eligible EV) or needs the employee contribution method. Then run the same car through a car loan comparison. The lease should still win after all fees — if it does not, walk away. Because this is a financial decision with real money at stake, consider getting independent financial advice before committing.
Bottom Line
A novated lease is worth it for a full-time employee on a decent salary who was going to buy a new car anyway — and it is a standout deal for an eligible electric vehicle. It is not worth it on a low income, with a shaky job, or when the provider’s interest rate and fees eat the tax saving. The tax break is real, but it is not magic: compare the total cost in writing, plan for the residual, and you will know your answer.