The average credit score in the country sits at around 850 on the Equifax scale of 0 to 1,200. That puts the typical person in the “very good” band. But that single number hides a lot: your score depends on which bureau checks it, your age, and even where you live. People in their 60s average over 900, while people under 30 average closer to 730.
In this guide, we explain what the average credit score is, how it differs by age and state, what the score bands mean, and what to do if your score is below average. You can check your own score for free — see Moneysmart’s guide to credit scores and credit reports for how the official system works.
What Is the Average Credit Score?
There is no single official national average, because the country has two main credit reporting bureaus — Equifax and Experian — and each uses its own scale and formula. So the “average” you see quoted depends on who measured it and when.
On the Equifax scale, which runs from 0 to 1,200 and is the one most banks use for home loans, the national average is roughly 850 to 860. Equifax data puts the average for women at 868 and for men at 850. Other sources that blend bureaus or use a different scale report lower numbers, often around 700 to 735, which is why you will see different figures quoted online. They are not necessarily wrong — they are just measuring on a different scale.
The key point is where the average falls: on the Equifax scale, the average person sits in the “very good” band, not just “good”. If your score is above 726, you are already above the middle of the pack.
Average Credit Score by Age
Age makes the biggest difference to credit scores. Young people have short credit histories, so their scores start low and climb steadily over decades. Based on Equifax data, the averages by age group are:
| Age group | Average credit score (Equifax, 0–1,200) |
|---|---|
| 18–30 | 731 |
| 31–40 | 829 |
| 41–50 | 868 |
| 51–60 | 918 |
| 61–70 | 935 |
The jump from the under-30s to the 30s is the biggest of all — nearly 100 points. That is mostly because people in their 30s start taking out mortgages and building a longer repayment history. If you are young and your score looks low, it is usually a matter of time and steady repayments, not something you did wrong.
Average Credit Score by State
Scores also vary by state and territory, though the gaps are smaller than the age gaps. Based on the same Equifax data:
| State / territory | Average credit score (Equifax, 0–1,200) |
|---|---|
| ACT | 900 |
| Tasmania | 882 |
| Victoria | 881 |
| South Australia | 874 |
| New South Wales | 873 |
| Western Australia | 871 |
| Queensland | 848 |
| Northern Territory | 825 |
The ACT has the highest average at 900, while the Northern Territory has the lowest at 825. Even so, every state average sits in the “very good” band. Where you live does not decide your score — your repayment history does.
Credit Score Bands Explained
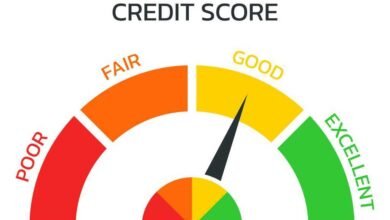
Both bureaus sort scores into bands with names like “average”, “good” and “excellent”. The most quoted bands are Equifax’s, on its 0 to 1,200 scale:
| Band | Equifax score (0–1,200) | What it usually means |
|---|---|---|
| Below average | 0–509 | Some lenders may decline you; higher rates likely |
| Average | 510–621 | Some options available, but choice is limited |
| Good | 622–725 | Standard lending at normal rates |
| Very good | 726–832 | Most lenders will approve you |
| Excellent | 833–1,200 | Best rates and widest choice |
Experian uses its own bands, and its scale has recently moved to 0–1,200 as well. Its “good” range starts around 500 and “excellent” starts around 800. The old bureau illion, which also scored on a 0–1,000 scale, has now merged into Experian, so there are effectively two main bureaus left.
One thing to keep in mind: the exact cut-offs have shifted slightly over the years, so older guides may show slightly different numbers. The bands above are the current ones most lenders refer to. If you want the full picture, read our guide on what a credit score is and how it differs from a credit report.
Why Your Score May Differ Between Bureaus
It is normal to have a different score at Equifax and Experian. Three reasons explain most of the gap:
- Different scales. Even though both now run to 1,200, their formulas are not the same, so the same credit file can produce different numbers.
- Different data. Not every lender reports to both bureaus, and updates arrive at different times. A loan that appears on one file may not yet appear on the other.
- Different weighting. Each bureau weighs repayment history, defaults, credit enquiries and credit limits slightly differently.
Lenders usually check only one bureau, so a lower score at the other one does not automatically hurt you. What matters is the score the lender actually sees.
What Is a Good Credit Score?
A “good” score is any score that gets you approved at normal rates — on the Equifax scale, that is 622 and above. A “very good” score of 726 or more puts you above the national average and usually unlocks better rates. An “excellent” score above 833 gives you the widest choice.
But the number alone is not everything. Lenders also look at your income, your debts, your employment history and whether you have missed payments. A good score with a shaky application can still be declined, and a middling score with a strong application can still be approved.
What Happens If Your Score Is Below Average?
A below-average score — under 510 on the Equifax scale — can make borrowing harder. You may face higher interest rates, smaller credit limits, or be turned down outright. It can also make it harder to get a rental property or a phone plan, since some landlords and providers check credit too.
The good news is that a low score is not permanent. Negative marks like defaults generally stay on your file for five years, but their impact fades over time, and positive behaviour — paying on time, every time — starts improving your score within months.
How to Improve a Below-Average Credit Score
There is no quick fix, but these steps work steadily over time:
- Pay every bill on time. Repayment history is the biggest factor in your score under comprehensive credit reporting.
- Check your report for errors. Mistakes happen — a wrong default or an old address can drag your score down. You can ask the bureau to fix errors for free.
- Lower your credit card limits. Lenders judge you on the limit you could use, not the balance you owe, so a lower limit looks safer.
- Pay off old debts. Clearing overdue accounts helps, even if the record stays on your file for a while.
- Limit new applications. Each credit enquiry leaves a mark, so space applications out and only apply when you need to.
- Keep good accounts open. A long history of well-managed accounts works in your favour — closing your oldest card can shorten your history.
How to Check Your Credit Score for Free
You can check your score for free, and checking it yourself does not lower it. Equifax offers a free score through GetCreditScore, while Experian’s score is available free through ClearScore and CreditSavvy. You are also entitled to a free copy of your full credit report from each bureau every three months.
Our step-by-step guide explains how to check your credit score for free, and our round-up of the best free credit score apps compares the main options. If you are worried that checking will hurt your score, it will not — read does checking your credit score lower it for the full explanation.
Frequently Asked Questions
What is the average credit score?
On the Equifax scale of 0 to 1,200, the national average is roughly 850 to 860, which falls in the “very good” band. Figures from other bureaus look lower because they use different scales.
Is a credit score of 700 good?
On the Equifax scale, 700 is in the “good” band (622–725) — close to “very good”. On the Experian scale, 700 is “very good”. Either way, a 700 is a solid score that most lenders will accept.
Is a credit score of 800 excellent?
On the Experian scale, 800 and above is “excellent”. On the Equifax scale, 800 is in the “very good” band, and “excellent” starts at 833.
What is the highest credit score possible?
The highest possible score is 1,200 on both the Equifax and Experian scales. Very few people reach it — only around 1 to 2 percent score above 950 on the Equifax scale.
Does everyone have the same credit score at every bureau?
No. Equifax and Experian collect different data and use different formulas, so your scores will differ. That is normal, and lenders usually check only one of them.
This article is general information only and is not personal financial advice. If you need help with debt or a credit problem, consider speaking with a free financial counsellor by calling the National Debt Helpline on 1800 007 007.